What is the market overview of the Contact Centers For Pharma Market?
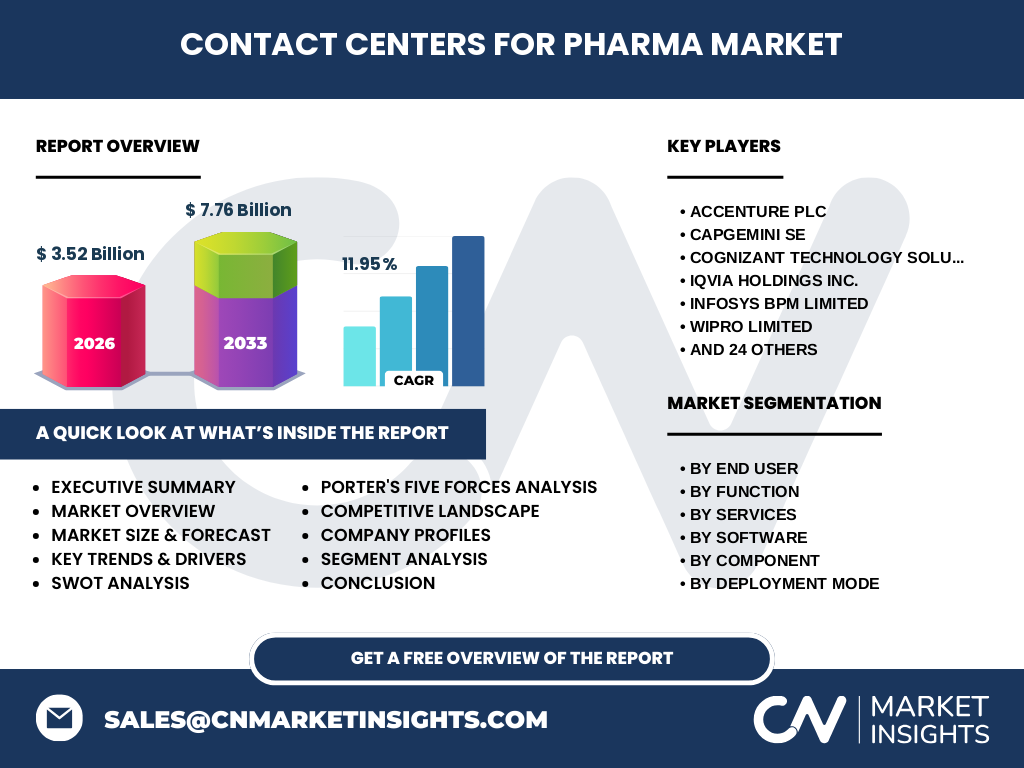
Our analysis indicates that the Contact Centers For Pharma Market stands at 3.52 Billion in 2026, serving as the critical communication backbone between pharmaceutical manufacturers, Contract Research Organizations, and healthcare providers. Specialized pharma contact centers manage complex workflows encompassing adverse event reporting under FDA and EMA mandates, medical information inquiries, and patient adherence programs for complex biologics and rare disease therapeutics.
Structural Growth Drivers and Restraints in the Contact Centers For Pharma Market
Growth is propelled by the surging complexity of clinical trials and the proliferation of specialty pharmaceuticals requiring intensive patient support. However, stringent compliance frameworks such as HIPAA and GDPR act as notable restraints, demanding rigorous data security. Major opportunities lie in deploying cloud-based platforms integrated with CRM systems like Veeva Systems to streamline adverse event intake while reducing operational latency.
Emerging Trends Transforming the Contact Centers For Pharma Market
The industry is witnessing an accelerated shift toward omnichannel engagement models and automated Adverse Event Reporting workflows. IntelePeer Cloud Communications LLC and Talkdesk Inc. are pioneering conversational AI solutions that handle routine medical information requests securely, allowing human agents to focus on high-touch patient adherence counseling for oncology and immunology portfolios.
How did the COVID-19 pandemic impact the Contact Centers For Pharma Market recovery trajectory?
The pandemic exposed vulnerabilities in legacy on-premises infrastructure, forcing a rapid, irreversible migration to cloud-based architectures. EVERSANA and ProPharma Group adapted swiftly by deploying remote, specialized clinical communication teams. This crisis catalyzed a resilient recovery trajectory, embedding omnichannel infrastructure as the permanent operational standard across top-tier pharmaceutical enterprises.
Competitive Benchmarking: Major Players in the Contact Centers For Pharma Market
Market concentration features a mix of global BPO giants and niche life sciences specialists. IQVIA Holdings Inc., Syneos Health Inc., and Inizio Engage leverage deep clinical data integration to provide differentiated medical information services. Meanwhile, technology providers like Genesys Telecommunications Laboratories Inc. and NICE Ltd. supply the foundational software powering these complex, compliant customer interaction ecosystems.
Executive Summary of Contact Centers For Pharma Market Findings
Our research forecasts the Contact Centers For Pharma Market to surge from 3.52 Billion in 2026 to 7.76 Billion by 2033, expanding at a robust CAGR of 11.95%. This expansion is heavily driven by increasing demand for specialized patient adherence programs and cloud-based omnichannel software adoption across major pharmaceutical companies and contract research organizations globally.
What is the projected market forecast for Contact Centers For Pharma Market through 2033?
Driven by rising investments in specialized medical information and pharmacovigilance outsourcing, the market is set to expand aggressively. Based on our research, the Contact Centers For Pharma Market will achieve the projected 7.76 Billion valuation by 2033, maintaining an impressive 11.95% CAGR as pharmaceutical firms increasingly prioritize outsourced, cloud-deployed patient support services over legacy in-house operations.
Segmentation Analysis of the Contact Centers For Pharma Market
Market segmentation spans multiple dimensions critical for strategic targeting: By End User: Pharmaceutical Companies, Contract Research Organizations, Healthcare Providers, and Other End Users. By Function: Customer Support, Medical Information, Adverse Event Reporting, Patient Adherence, Sales Support, and Other Function. By Services: Implementation And Integration Services, Consulting And Advisory Services, Managed Contact Center Services, Training And Support Services, and Maintenance And Optimization Services. By Software: Omnichannel Contact Center Software, Customer Relationship Management Integration Software, Interactive Voice Response Software, Workforce Management Software, and Analytics And Reporting Software. By Component: Software and Services. By Deployment Mode: On Premises and Cloud-Based. By Enterprise Size: Large Enterprises and Small And Medium Enterprises.
Regional Market Distribution and Performance Patterns
Geographic performance reflects the density of pharmaceutical R&D hubs and regulatory stringency. North America dominates market revenue share, bolstered by stringent FDA pharmacovigilance requirements and high adoption rates of advanced CRM integration software among large enterprises. Europe follows closely, driven by EMA compliance mandates, while the Asia-Pacific region exhibits the fastest growth due to expanding clinical trial activities and rising healthcare infrastructure investments.
In-Depth Regional Review and Localized Market Constraints
North American operations emphasize cloud-based omnichannel solutions to manage sprawling patient assistance programs. In contrast, European markets navigate complex cross-border data privacy regulations under GDPR, favoring localized data hosting. Meanwhile, emerging markets in Asia-Pacific require tailored multilingual support and robust telecom infrastructure partnerships to bridge accessibility gaps in remote healthcare provider networks.
Strategic Positioning of Leading Companies in the Contact Centers For Pharma Market
Industry leaders combine regulatory compliance expertise with cutting-edge technology. Accenture plc, Capgemini SE, and Cognizant Technology Solutions Corporation utilize robust analytics and reporting software to optimize omnichannel workflows. Meanwhile, specialized players like EVERSANA and Inizio Engage integrate commercialization services directly with managed contact center operations to deliver end-to-end pharmaceutical support.
Porter's Five Forces Analysis of the Contact Centers For Pharma Market
Bargaining power of buyers is moderate to high, as large pharmaceutical firms demand strict SLA compliance and HIPAA adherence. Threat of new entrants remains low due to high regulatory barriers, specialized pharmacovigilance training requirements, and steep CRM integration costs. Rivalry among established players like Concentrix Corporation, Teleperformance SE, and Genpact Limited is intense, driving continuous technological innovation.
SWOT Analysis of the Contact Centers For Pharma Market
Strengths include deep domain expertise in adverse event reporting and established relationships with major pharma sponsors. Weaknesses involve high vulnerability to data breaches and steep training overheads. Opportunities lie in expanding cloud-based patient adherence solutions in emerging economies, while threats stem from evolving data localization laws and aggressive pricing pressure from generic drug manufacturers.
Value Chain Analysis from Raw Data to End-User Delivery
The value chain originates with software and cloud infrastructure providers like RingCentral Inc. and Talkdesk Inc., feeding into specialized BPO providers such as PharmaCentra LLC and Ubiquity Global Services Inc. These providers ingest raw clinical trial and commercial data, process adverse events through strict regulatory filters, and deliver actionable insights to pharmaceutical companies, CROs, and healthcare providers.
Investment Insights and High-Potential Areas for Stakeholders
Our analysis indicates that investors should prioritize companies offering proprietary AI-driven analytics and reporting software tailored for adverse event intake. High-potential areas include managed contact center services optimized for rare disease patient adherence and cloud-based omnichannel implementations that ensure seamless CRM integration for large pharmaceutical enterprises.
Conclusion and Key Takeaways for Market Entrants
The Contact Centers For Pharma Market represents a high-growth, highly regulated landscape projected to reach 7.76 Billion by 2033. Success hinges on mastering omnichannel software deployment, ensuring flawless regulatory compliance across FDA and EMA jurisdictions, and partnering with established leaders like Veeva Systems, IQVIA, and Teleperformance to capture market share.
Research Methodology for Baseline Estimates and Data Triangulation
Baseline estimates are derived through rigorous data triangulation, combining primary stakeholder interviews with C-level pharma executives and contact center operators, secondary macroeconomic indicators, and trade registry data. Market size and forecast models reconcile top-down macroeconomic sizing with bottom-up revenue aggregation across key market segments and geographic regions.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for the Contact Centers For Pharma Market from 2026 through 2033. Analysis encompasses all specified segments—including software, services, deployment modes, functions, and end-user types—while explicitly excluding generalized retail and financial contact center operations to maintain strict life sciences industry focus.
Recent Developments and Strategic Moves Across the Industry
Recent strategic initiatives highlight a strong industry push toward automated compliance and AI integration. Major players have announced key partnerships; for instance, technology innovators like NICE Ltd. and Genesys have integrated advanced workforce management software specifically tailored to pharmaceutical compliance workflows, while major BPOs continue expanding their cloud-based infrastructure footprints.